
Digital arrest scams are under Supreme Court scrutiny after losses of about ₹800 crore in 2026, even after recoveries. The case connects cybersecurity with bank accountability and individual rights.
Quick answer: Digital arrest scams use fake police or investigation officials to intimidate victims into transferring money. At an October 29 hearing, the Supreme Court pressed the Reserve Bank of India to finalise safeguards against mule accounts. Losses in 2026 totalled about ₹800 crore even after recoveries, underlining the need for prevention and compensation.
What did the Supreme Court say?
At its 29 October hearing, the Supreme Court pressed the Reserve Bank of India (RBI) to finalise its Know Your Customer (KYC) Amendment Directions, 2026. Chief Justice of India Surya Kant questioned why people continued to fall for such frauds despite warnings and court orders.
The Court also insisted that banks compensate victims and suggested automatic police reporting and physical verification of unusual transactions. However, these hearing developments should not be confused with a final judgment on every aspect of compensation.
The Attorney-General assured the Court that the directions would take effect by 31 December 2026. Until then, the assurance is a timetable, not evidence that the directions are already in force.
How do digital arrest scams work?
Fraudsters impersonate police or Central Bureau of Investigation (CBI) officers and threaten victims with arrest over video calls. They exploit fear of law enforcement to pressure victims into transferring money.
Older citizens can be particularly vulnerable when a caller claims official authority. Moreover, the editorial argues that perceptions of high-handed policing can make such threats credible; warnings alone may therefore fail.
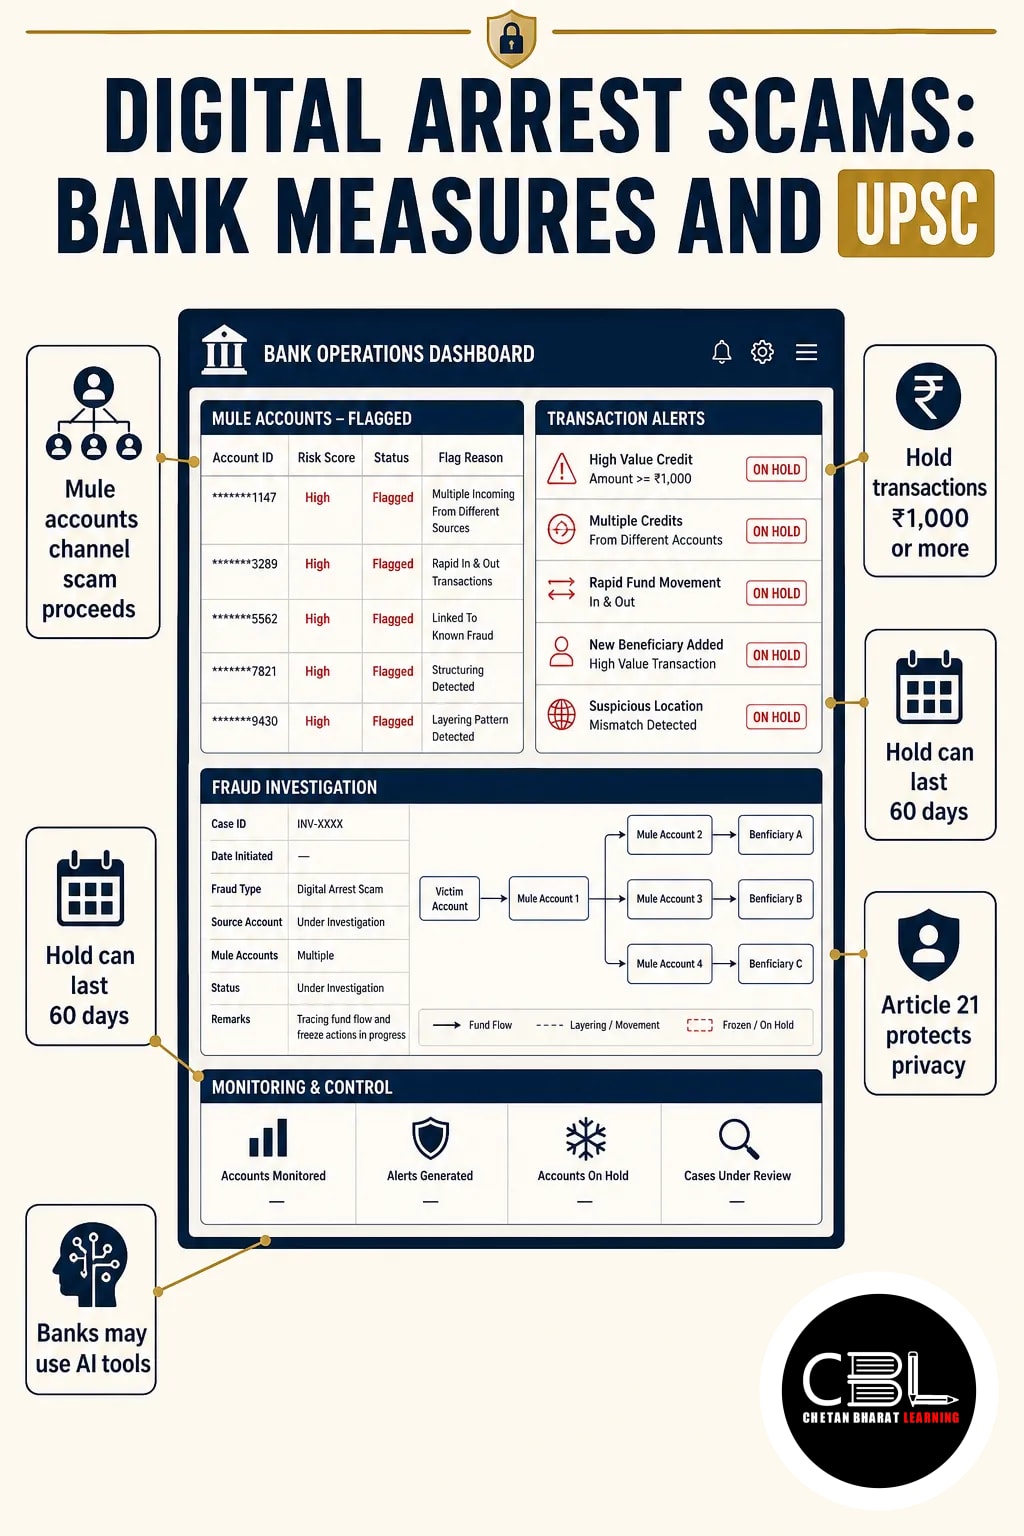
A mule account receives or channels proceeds on behalf of fraudsters, helping obscure the money trail. CBI investigations have identified these accounts as central to laundering scam proceeds; in some cases, bank staff helped open them. For a related impersonation risk, read about deepfake-enabled scams.
What safeguards and legal principles apply?
The proposed directions seek to identify suspicious accounts, while existing safeguards distinguish unauthorised transactions from coerced transfers.
| Provision or measure | Relevance |
|---|---|
| RBI KYC Amendment Directions, 2026 | The proposed directions require banks to flag suspected mule accounts and place temporary debit holds. |
| Suspicious transaction hold | A transaction of ₹1,000 or more that is unusual for the declared profile, or linked to a reported account, can be held for up to 60 days; police can direct a longer hold. |
| RBI zero-liability circular, 2017 | It covers unauthorised transactions; the editorial identifies a gap for victims coerced into making transfers themselves. |
| Article 21 of the Constitution | It protects life and personal liberty; the constitutional right to privacy is relevant when authorities collect or verify personal information. |
In addition, banks can examine transaction histories with artificial intelligence (AI) tools to identify anomalies faster. An alert, however, signals risk rather than proving that an account holder knowingly joined a fraud. The wider role of technology in security is also discussed in CBL’s coverage of telecom AI cybersecurity reporting.
Why is compensation difficult?
Compensation is difficult because a victim may personally authorise a transfer under coercion, even though a fraudster controls the decision through threats. Thus, the existing unauthorised-transaction framework may not provide recourse in such cases.
Bank liability for deficient due diligence can create incentives to prevent fraud. However, if banks fear liability for every missed case, they may flag excessive numbers of legitimate accounts. A fair framework must therefore examine both the bank’s conduct and the circumstances of the transfer.
What are the risks of wider account monitoring?
Broad monitoring can stop suspicious flows, but it can also restrict legitimate access to money and expose personal information.
- Financial exclusion: Small traders and Jan Dhan account holders may unknowingly receive transfers linked to mule accounts; prolonged restrictions can disrupt their transactions.
- False positives: An unusual transfer is not necessarily fraudulent, so automated detection needs human review.
- Privacy: Automatic police reporting and physical verification can expand scrutiny of innocent account holders; therefore, safeguards must limit unnecessary disclosure.
- Disproportionate burden: Genuine customers should not bear the consequences of bank due diligence failures; moreover, they need a way to contest restrictions.
What should the policy response prioritise?
The response should combine targeted banking controls with accountable policing and cross-border cooperation.
- Proportionate restrictions: Use risk-based alerts, timely human review and clear procedures to lift mistaken holds; consequently, genuine customers face less disruption.
- Fair compensation: Specify how bank due diligence failures affect liability and give victims accessible complaint and review mechanisms.
- Privacy safeguards: Limit information sharing to what an investigation requires and record the reasons for intrusive verification.
- Public trust: Explain that fraudsters impersonate authorities and improve respectful police engagement; moreover, communications should reach older persons and account holders with limited digital familiarity.
- Cross-border action: Pursue cooperation with Myanmar, Cambodia and Laos, where the editorial identifies scam compounds and trafficking of Indians.
Overall, bank intervention can interrupt the money trail, but it cannot by itself dismantle coercive networks operating across borders. The policy test is whether authorities prevent fraud without treating every unusual transaction as proof of criminality.
Source: The Hindu Editorial, 2 November 2026
- Telecom AI Cybersecurity Reporting: TRAI Draft for UPSC (2 Nov 2026)
- Deepfake Scams: Cyberpark Session and UPSC Analysis (30 Oct 2026)
State PCS General Studies may test cybercrime, police accountability and coordination with banks. Candidates can also examine how state authorities communicate fraud warnings without penalising genuine account holders.
Prelims Practice Corner
Mains Practice Questions
Frequently Asked Questions
What is a digital arrest scam?
It is a fraud in which impostors threaten a person with arrest to extract money. For example, they may pose as police or investigation officers on a video call.
What is a mule account?
A mule account receives or channels money for others, including fraud proceeds. Consequently, investigators consider such accounts important to tracing scam funds.
Does the 2017 RBI zero-liability circular cover every coerced transfer?
No, because the circular covers unauthorised transactions. The editorial identifies a gap where victims themselves transfer funds under coercion.
When are the proposed KYC directions expected to take effect?
By 31 December 2026, according to the Attorney-General’s assurance to the Court. However, that assurance does not establish that the directions are already in force.
Related Current Affairs
Preparing for UPSC, PCS or HCS?
Talk to a mentor at Chetan Bharat Learning, Chandigarh. Free guidance on choosing the right exam and building a study plan.
Chat on WhatsAppCall 97793 53345UPSC / IAS / PCS coaching in Chandigarh · Trusted by aspirants across Punjab & Haryana
 Ananya RanaIAS · AIR 60
 Aditya SharmaIAS · AIR 70
 Ria Kaur SethiIPS · AIR 89
 Aman AloonIRS · AIR 295
 Sumer Singh VirkIRS · AIR 335
 Shivani PanchalIAS
Leave a Reply
You must be logged in to post a comment.