
CBIC GST arrests must stop under instructions from the Central Board of Indirect Taxes and Customs (CBIC) to its Goods and Services Tax (GST) field formations. The directive also changes how central officers handle transit inspections and low-value notices. For related policy coverage, visit economy current affairs.
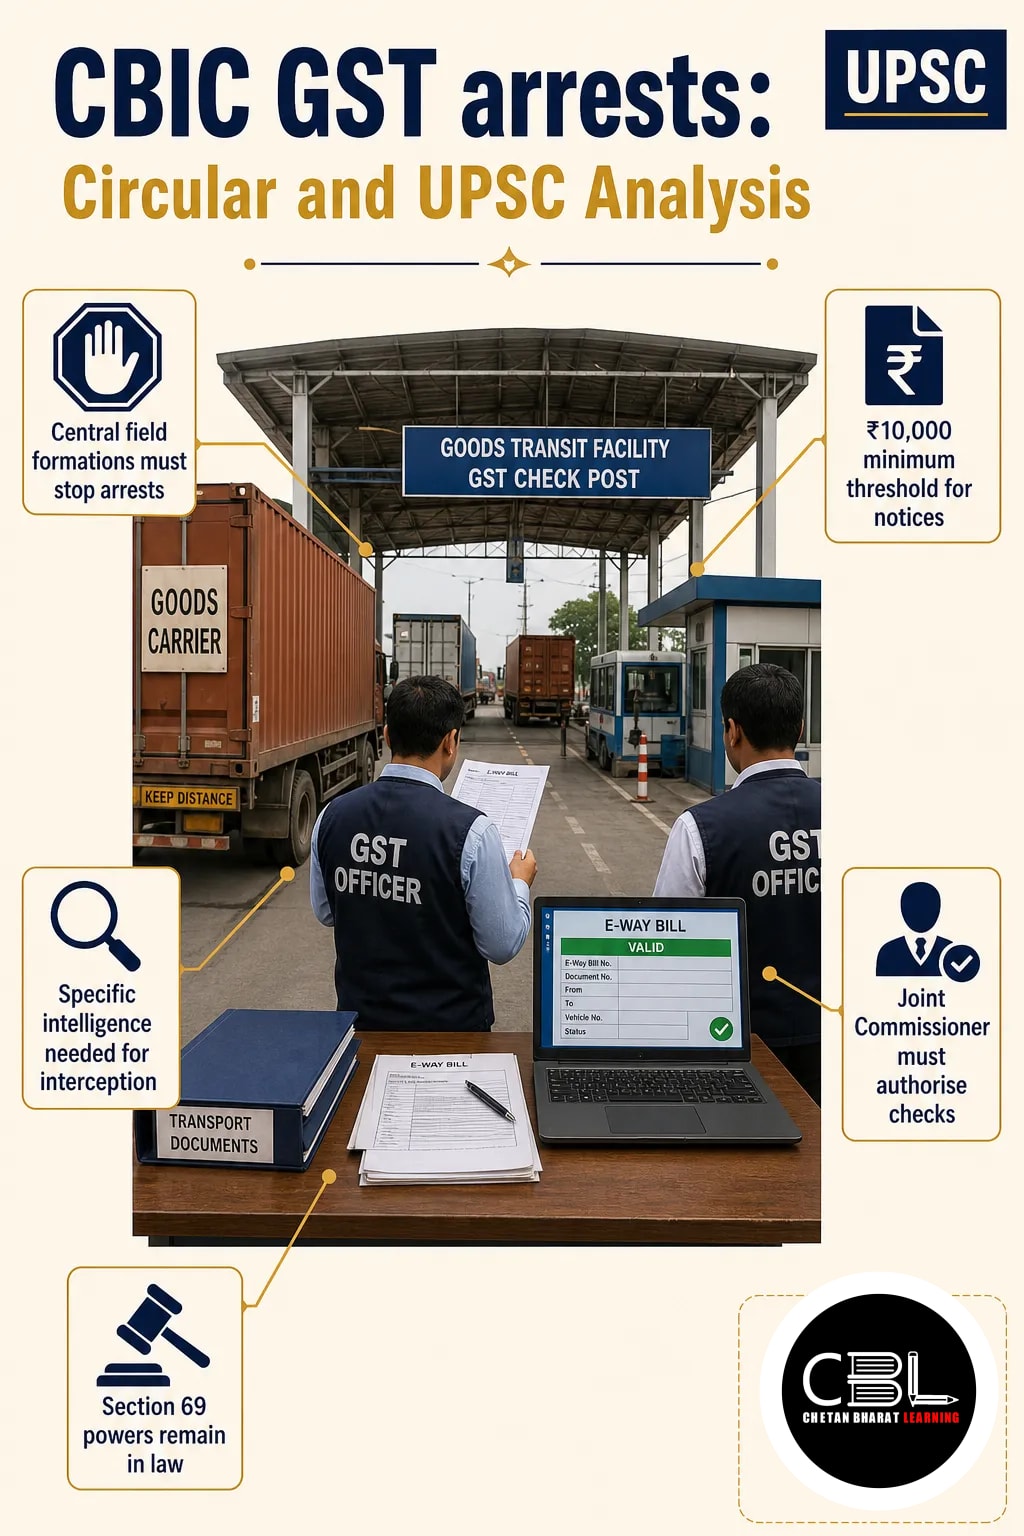
Quick answer: CBIC GST arrests are to stop immediately in central field formations, ahead of proposed amendments expected from 1 April 2027. Following the GST Council’s 8 October recommendations, CBIC also directed intelligence-based vehicle checks and a ₹10,000 minimum threshold for show-cause notices. The interim instructions do not themselves amend the law.
What has CBIC directed on GST arrests?
CBIC has told all Central GST field formations not to carry out further GST arrests. Its instruction implements the Council’s recommended withdrawal of arrest powers as an interim administrative measure.
The Council proposed omitting Section 69 of the Central Goods and Services Tax Act, 2017, which provides for arrest after the Commissioner’s approval. However, the directive does not itself delete that provision. The proposed legislative changes also require corresponding amendments to state GST laws.
The Council made its recommendations at its 57th meeting on 8 October. It proposed that the amended provisions take effect on 1 April 2027. Meanwhile, the Centre decided that CBIC formations should implement the reforms before the amendments take effect.
What are the main changes in the directive?
The directive covers arrests, checks on goods in transit and show-cause notices. Their immediate operation through CBIC instructions differs from the proposed statutory changes.
| Measure | Instruction or proposal |
|---|---|
| Arrests | Central field formations must stop further arrests; the Council proposed omitting Section 69. |
| Transit checks | Interception requires specific intelligence and authorisation at the prescribed rank. |
| Show-cause notices | Notices may not be issued when the combined amount involved is below ₹10,000. |
| Monitoring | Principal Chief Commissioners and Chief Commissioners must monitor implementation and inform the Board of difficulties. |
For the notice threshold, officers add amounts under the Central, State, Integrated and Union Territory GST Acts, plus GST compensation cess. Moreover, the Council recommended that the threshold apply retrospectively. Read more about GST registration and notice reforms.
How will e-way bill checks work?
CBIC requires specific intelligence and senior authorisation before a conveyance can be intercepted. An officer at least at the rank of Joint Commissioner must authorise the action and record written reasons to believe that the transport violates the Act or its rules.
The Council recommended checks by tax officers from the supplier’s or recipient’s state. Where neither party is registered or located in the authorising officer’s state or Union Territory, a different procedure applies.
- Passing information: If the intercepting officer finds a prima facie violation after checking documents, the goods and conveyance must pass unhindered. The officer then sends the information to the proper jurisdictional officer for examination and action.
- Exception: If neither an e-way bill nor a document showing origin or destination exists, the intercepting officer may inspect, detain or seize the goods or conveyance irrespective of jurisdiction.
The directive restricts detention or seizure in transit to the grounds it specifies. Therefore, the reform limits random checks while retaining a route for action where essential transport documents are absent.
Why do the reforms matter for governance?
The reforms seek to reduce compliance costs and make tax administration less intrusive. They also raise questions about legal authority, enforcement and coordination.
- Taxpayer safeguards: Stopping arrests and requiring recorded reasons for interception can reduce coercive encounters. Consequently, businesses face fewer interruptions from checks without specific intelligence.
- Lower-value disputes: The notice threshold aims to reduce litigation and the cost of responding to small demands. However, officers must calculate the combined amount across the specified GST components and cess.
- Enforcement capacity: Intelligence-led checks can focus attention on suspected violations. At the same time, authorities need reliable information and timely follow-up by jurisdictional officers.
- Centre–state coordination: Goods often cross jurisdictions, so information must reach the proper officer. Moreover, CBIC’s instruction addresses central field formations; corresponding legal changes require state action.
What are the legal concerns and the way forward?
The main concern is the gap between an administrative instruction and an amendment to legislation. Legal experts had questioned whether Council recommendations alone had legal backing before the proposed amendments.
Accordingly, aspirants should distinguish three stages: the Council’s recommendation, CBIC’s interim direction to its officers, and enactment of the required amendments. A direction to officers not to exercise a power is not the same as removing that power from the statute.
Going forward, clear legislative changes and coordinated state implementation can reduce uncertainty. In addition, officers need consistent procedures for written authorisation, information sharing and threshold calculations. Senior commissioners can use the prescribed monitoring process to identify implementation difficulties.
Source: Indian Express Business, 30 October 2026
Punjab PCS and Haryana HCS can test the roles of state tax authorities and the GST Council. Also, the transit-check rules illustrate why neighbouring states need coordination when goods cross jurisdictional boundaries.
Prelims Practice Corner
Mains Practice Questions
Frequently Asked Questions
Have GST arrest powers already been removed from the CGST Act?
No, because CBIC’s instruction does not itself amend Section 69. The Council has recommended omitting the provision through legislation.
What is the new threshold for GST show-cause notices?
The minimum threshold is ₹10,000. For this calculation, the specified GST amounts and compensation cess are added together.
When were the proposed GST amendments expected to take effect?
The GST Council proposed 1 April 2027. Meanwhile, CBIC instructed its field formations to implement the reforms as an interim measure.
Can tax officers still intercept goods in transit?
Yes, because the directive permits interception on specific intelligence with the required authorisation and written reasons. It also sets jurisdictional procedures and a document-related exception.
Related Current Affairs
Preparing for UPSC, PCS or HCS?
Talk to a mentor at Chetan Bharat Learning, Chandigarh. Free guidance on choosing the right exam and building a study plan.
Chat on WhatsAppCall 97793 53345UPSC / IAS / PCS coaching in Chandigarh · Trusted by aspirants across Punjab & Haryana
 Ananya RanaIAS · AIR 60
 Aditya SharmaIAS · AIR 70
 Ria Kaur SethiIPS · AIR 89
 Aman AloonIRS · AIR 295
 Sumer Singh VirkIRS · AIR 335
 Shivani PanchalIAS
Leave a Reply
You must be logged in to post a comment.