The hydel water tax verdict has brought legislative competence and fiscal federalism into focus. The ruling is relevant to polity and constitutional governance.
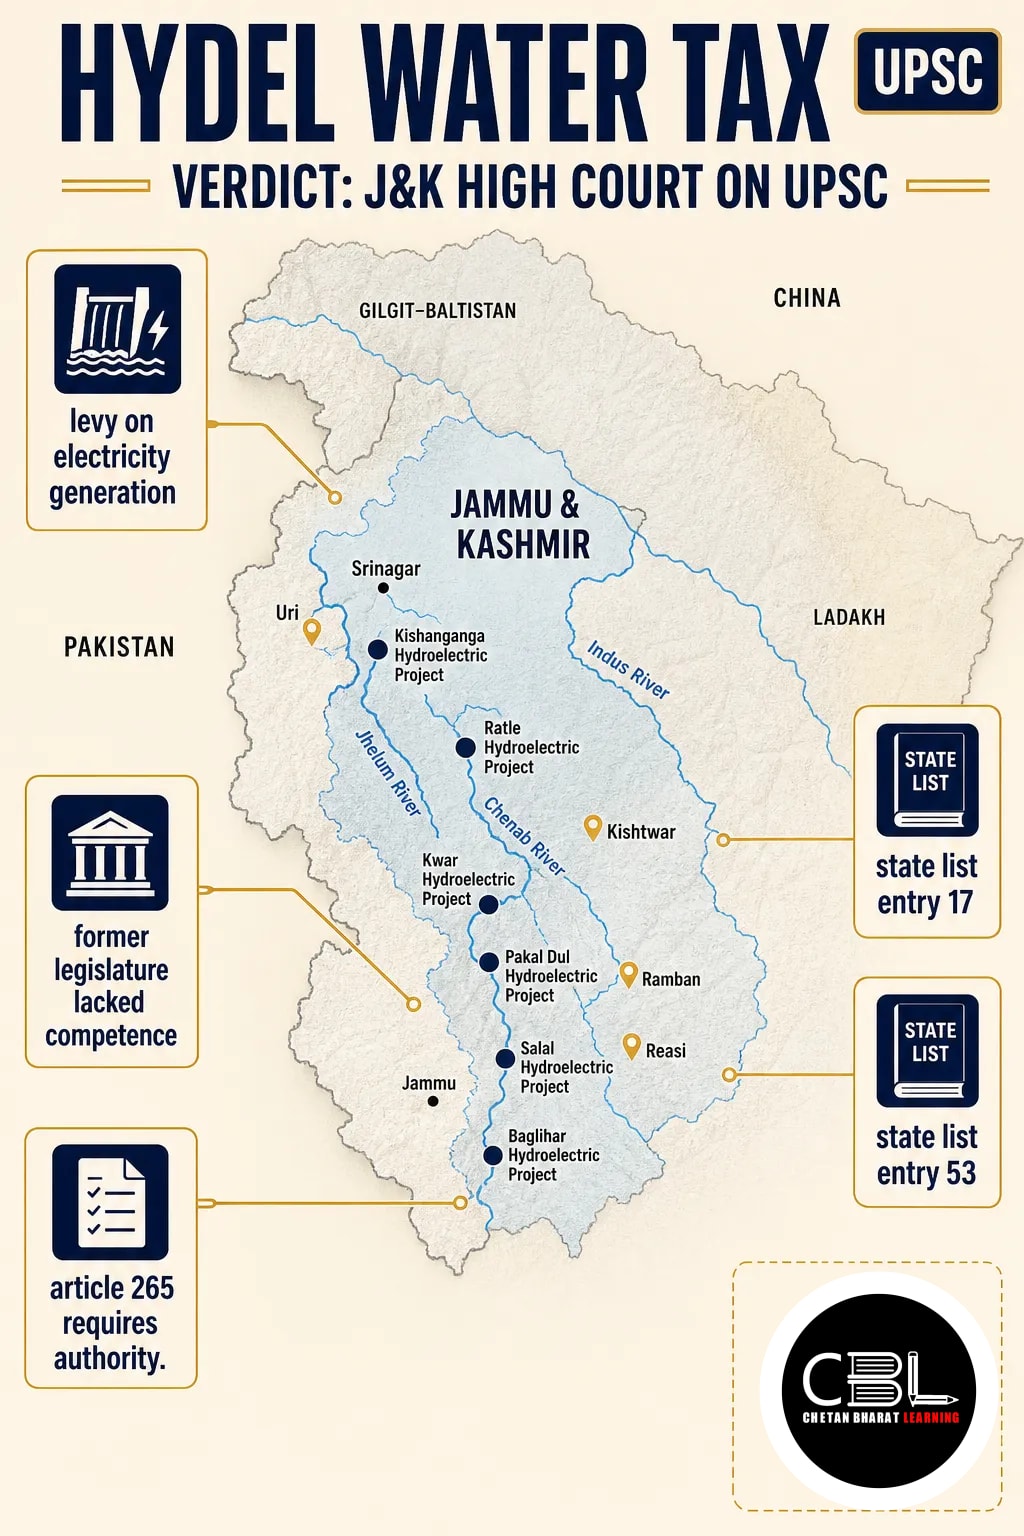
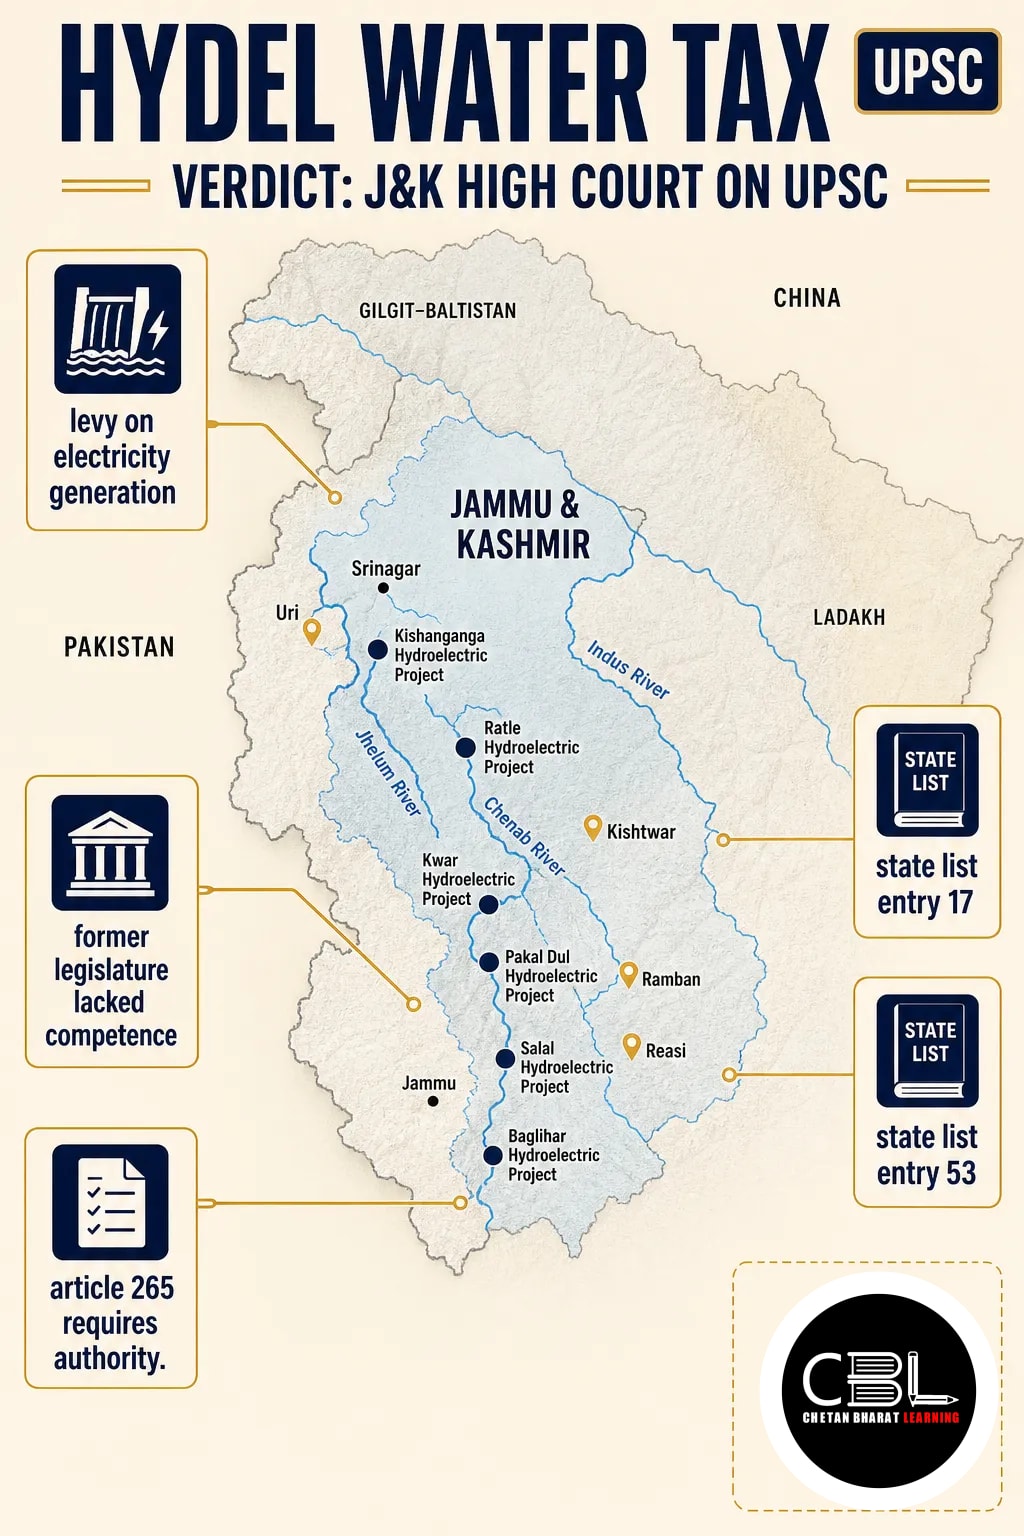
Quick answer: On 29 October 2026, the Jammu & Kashmir and Ladakh High Court invalidated provisions imposing a hydel water tax on electricity generation. It held that the former state’s legislature lacked competence to impose this levy. The court also quashed demand notices against three hydropower firms in Jammu and Kashmir.
What did the High Court hold?
The court held that the challenged levy was, in substance, a tax on electricity generation. Therefore, the former Jammu and Kashmir legislature lacked competence to impose it under the constitutional framework.
The division bench comprised Justice Rajnesh Oswal and Justice Sanjay Dhar. It struck down provisions of the Jammu and Kashmir Water Resources (Regulation and Management) Act, 2010, to the extent that they imposed this tax. In addition, it quashed the petitioners’ demand notices.
The ruling does not, on the supplied facts, establish that every water-related charge is unconstitutional. Instead, the court examined the particular levy and its statutory setting. For related context, see CBL’s analysis of the J&K water charges verdict.
What was the background of the case?
Three hydropower firms challenged the 2010 Act and its rules through a writ petition. They argued that water usage charges for electricity generation exceeded the former state legislature’s powers.
The petitioners were Mass N Ergy Private Limited, Magpie Hydel Construction Operation Industries and Choudhary Power Projects Private Limited. The bench had reserved judgment after hearing the challenge. The Act was passed by the legislature of the former state; the ruling concerns its application in the present Union Territory.
Why did the court examine the substance of the levy?
The court examined the levy as a whole rather than treating its description as decisive. It considered the Act, the tariff notification and the statutory scheme together.
In the court’s reasoning, water use and hydropower generation formed one inseparable event under the scheme. Consequently, the levy was on generation in substance, not a charge for water use. This distinction matters because a legislature must have authority over the actual subject of a tax, not merely over a related regulatory subject.
For an examination answer, distinguish the taxable event from the resource involved. Water may be essential to generation, but that fact alone does not establish a power to tax generation.
Which constitutional provisions are relevant?
The Seventh Schedule separates legislative subjects across Union, State and Concurrent Lists, while Article 246 distributes legislative powers over them. The following provisions help explain the court’s reasoning:
| Article or entry | Relevance |
|---|---|
| Article 246 | Distributes legislative powers with reference to the Seventh Schedule. |
| State List, Entry 17 | Covers water-related subjects, subject to the specified Union List provision on inter-state rivers. The court treated it as a regulatory entry, not a water-taxing entry. |
| Concurrent List, Entry 38 | Lists electricity as a legislative subject; it should not be confused with a separate power to impose a particular tax. |
| State List, Entry 53 | Covers taxes on consumption or sale of electricity, not a general tax on its generation. |
| Article 265 | Requires authority of law for the levy and collection of tax. |
The court specifically found no corresponding taxing entry for water in the State List. Moreover, its conclusion concerned the former state’s competence under the constitutional framework examined in the case.
What are the implications for governance and federalism?
The verdict illustrates how constitutional limits shape resource governance and revenue choices. Its immediate effect is the removal of the challenged demands against the three petitioners.
- Legislative design: A law’s label cannot settle its validity; therefore, policymakers must identify the levy and its constitutional source.
- Regulation and taxation: Authority to regulate water does not automatically confer authority to tax it. Similarly, a general electricity entry should not be treated as a taxing entry.
- Project certainty: Quashing the notices clarifies the petitioners’ position under this scheme. However, the supplied material does not establish the financial value of the demands.
- Fiscal federalism: Resource-rich governments need lawful revenue options. At the same time, those options must respect the distribution of taxing powers.
What concerns and policy choices follow?
The central policy challenge is to reconcile resource management with constitutionally valid revenue measures. The ruling also calls for care before treating a charge and a tax as interchangeable.
First, governments should review the legal basis and taxable event of proposed levies before issuing demands. Second, they should distinguish regulatory costs from revenue-raising measures when designing any charge. However, a different label alone would not establish validity.
Finally, transparent assessment of hydropower’s local environmental and community effects can inform policy choices. Any alternative funding or regulatory mechanism would still require independent constitutional and statutory scrutiny. Thus, the verdict supports careful design rather than an assumption that all water charges are prohibited.
Source: The Indian Express, 30 October 2026
State PCS General Studies may test the distinction between water regulation and taxation under the Seventh Schedule. In addition, candidates should revise legislative competence and the constitutional basis of electricity-related taxes.
Prelims Practice Corner
Mains Practice Questions
Frequently Asked Questions
What did the court decide about the hydel water tax?
It invalidated the provisions to the extent they imposed a tax on electricity generation. It also quashed demand notices against the three petitioners.
Does State List Entry 17 itself authorise a tax on water?
No, because the court treated Entry 17 as a regulatory entry. It also found no corresponding water-taxing entry in the State List.
Did the verdict invalidate every possible water charge?
No such general conclusion follows from the supplied ruling summary. Instead, the court assessed the particular levy, tariff notification and statutory scheme.
Related Current Affairs
Preparing for UPSC, PCS or HCS?
Talk to a mentor at Chetan Bharat Learning, Chandigarh. Free guidance on choosing the right exam and building a study plan.
Chat on WhatsAppCall 97793 53345UPSC / IAS / PCS coaching in Chandigarh · Trusted by aspirants across Punjab & Haryana
Leave a Reply
You must be logged in to post a comment.